empty
01.10.2026 09:37 AM
Worst three months since late 2024

Just yesterday, Nasdaq 100 futures rose 1.2%, and S&P 500 futures gained 0.6%. By the close, however, indices finished mixed. Asian tech indices followed suit today: Japan's Nikkei 225 jumped 3.3%, and South Korea's Kospi added 1.7%. European futures nevertheless point to a modest decline at the open.

The rally was driven by an upbeat guide from Micron Technology, which confirmed that demand for AI chips remains strong. That benefits semiconductor manufacturers and their suppliers — and hurts investors who had been betting on a slowdown in the AI investment cycle. Micron reported historically high gross margins but warned they will narrow slightly due to rising labor costs.

This image is no longer relevant

Oil eased about 1% to roughly $89.55/bbl amid hopes that supply restoration from the Middle East will prove sustainable. The December Brent contract traded near $97. Although lower oil helped pause the Treasury sell-off, the 10-year yield stayed around 5.28%, close to Wednesday's peak. The 30-year yield even rose to about 5.62%, the highest since 2002. The past three months have been the worst on record in recent years for the US bond market.

Gold rose to roughly $4,185/oz, and silver gained 1.4% — a rare instance of safe havens rallying alongside risk assets. That pattern suggests investors are hedging inflation risk, not just equity risk. The dollar, meanwhile, pushed higher for a fourth consecutive session, supported by firm oil prices and US economic resilience.

The prospect of further Fed tightening, elevated oil prices (with the US as a net energy exporter), and uneven risk appetite are likely to keep supporting the dollar in the near term. The yen was the weakest G10 currency after post-BoJ meeting commentary disappointed investors expecting faster tightening.

In my view, Friday's US labor print will decide which force prevails — a Fed pause or continued pressure from fiscal spending and oil. With the dollar stronger, yields at multi-year highs, and the economy holding up, I see little reason to expect a reversal in equities or bonds before payrolls. If the jobs report undershoots expectations, the dollar will likely pull back, and long-bond yields could pause. If the labor market confirms resilience, bond pressure — especially on French paper — will persist, and the dollar should continue to strengthen against the yen and the New Zealand dollar in the coming sessions.

This image is no longer relevant

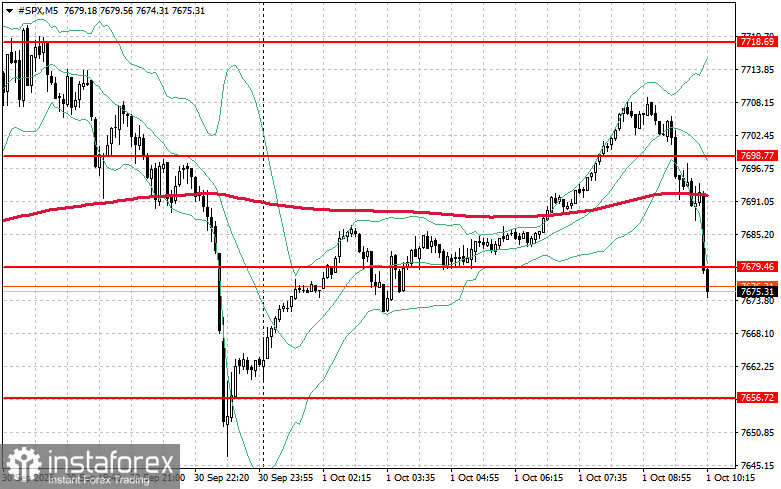
Technically, the S&P 500 chart indicates that the immediate task for buyers is to overcome the resistance level of $7,698. That would lead to renewed upside and open the way to $7,718. Maintaining control above $7,737 would further strengthen the bulls' case. On the downside, buyers must defend $7,679. A break below that level would likely push the index back to $7,656 and open the path to $7,631.

Jakub Novak,
Analytical expert of InstaForex
© 2007-2026
Earn on cryptocurrency rate changes with InstaForex
Download MetaTrader 4 and open your first trade
  • Grand Choice
    Contest by
    InstaForex
    InstaForex always strives to help you
    fulfill your biggest dreams.
    JOIN CONTEST
  • Chancy Deposit
    Deposit your account with $3,000 and get $1000 more!
    In October we raffle $1000 within the Chancy Deposit campaign!
    Get a chance to win by depositing $3,000 to a trading account. Having fulfilled this condition, you become a campaign participant.
    JOIN CONTEST
  • Trade Wise, Win Device
    Top up your account with at least $500, sign up for the contest, and get a chance to win mobile devices.
    JOIN CONTEST
  • 30% Bonus
    Receive a 30% bonus every time you top up your account
    GET BONUS

Recommended Stories

Can't speak right now?
Ask your question in the chat.
Widget callback